

EarnIn: Why Wait for Payday?
Activehours Inc.
- 4.7
- 137.90K Reviews
- 10.00M
- Downloads
- Free
- Price
Screenshots
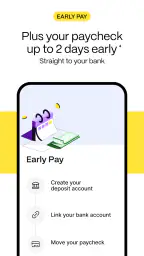
EarnIn: Why Wait for Payday? Pros and Cons
Pros
- Instant access to earned wages.
- No interest or hidden fees.
- User-friendly interface.
- Secure banking connections.
- Real-time financial insights.
Cons
- Limited to certain employers.
- Daily withdrawal limits apply.
- Requires bank account linking.
- Not a substitute for budgeting.
- May encourage overspending.
 Analysis by All-app
When a bill lands before payday, I can see why someone would look for a way to bridge the gap without turning to a credit card or a longer-term loan. EarnIn is a finance app from Activehours Inc. built around accessing part of your earned pay early. I’d think of it as a short-term cash-flow tool, not extra income: the money still comes from wages you have already worked for, so using it changes when cash arrives rather than how much you earn.
Start with the pay cycle, not the emergency
The app makes the most sense when a person has steady work and a predictable payday but faces an awkward mismatch between when expenses are due and when wages arrive. A grocery run, transit costs, or a utility bill can come at exactly the wrong point in the cycle. In that situation, getting some earned money sooner may help avoid a late payment or a more expensive borrowing option.
I would not make early access part of a normal monthly budget, though. If rent and routine bills regularly require money before payday, taking wages early can leave less to work with later. Before opening the app, I’d check the next pay date, the amount already committed to bills, and whether the expense can be moved or paid another way. That small pause helps distinguish a temporary timing problem from a budget shortfall that an advance cannot solve.
It is also worth asking whether the expense is genuinely urgent. For a necessary purchase that cannot wait, the convenience may matter. For something optional, waiting until payday is usually the cleaner choice because it avoids pulling money forward and having to adjust the rest of the pay period around it.
Follow the request through to the account
In practical use, the flow has several handoffs: I would provide employment and banking details, let the app work out what may be available from earned wages, request a cash-out if needed, and then make sure the money reaches the account in time for the bill. Those steps matter more than a polished home screen. A request is useful only if the user understands the amount, timing, and effect on the next pay cycle before relying on it.
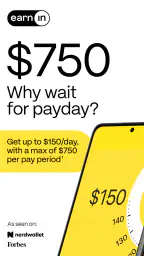
The store summary describes access of up to $150 a day, with a maximum of $1,000 per pay period. Those are ceilings, not a promise that every user can take the maximum whenever they want. I’d treat the amount shown for my own situation as the practical limit, and avoid planning an essential payment around the headline cap. A useful habit is to request only what closes the immediate gap, rather than taking the largest amount simply because it appears available.
Once money arrives, I’d mark the expense as covered and update my own budget so I do not mentally count the same wages twice. That is an easy detail to miss: an early cash-out can feel like a fresh deposit, but it is money from the upcoming paycheck. Keeping a note of what was advanced and which bill it covered makes the next payday easier to plan around.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
How It Works
So, the basic idea is pretty simple. Once you’ve got the app set up, EarnIn lets you tap into the money you've already earned but haven’t been paid yet. You link your bank account and employment details, and bam, you’re all set. The app tracks your work hours, and based on that, you can cash out up to $100 per day, with a weekly cap of $500. What’s cool is there are no hidden fees or interest rates. You just tip what you think is fair.
The Setup Process
Getting started with EarnIn is a breeze. You download the app, punch in your employment info, and link your bank account. The app uses your work schedule to calculate your earnings, so it knows how much you’re eligible to cash out. It’s pretty seamless, and within a few days, you’re good to go. Plus, the app’s interface is super user-friendly, which is always a win in my book.
For a first-time user, I’d approach setup as a review of the whole route rather than a quick form-filling exercise. Have your pay schedule and bank details to hand, then check that the work information you enter reflects how you are actually paid. If your hours vary, your schedule changes, or your pay is irregular, the amount the app can make available may not line up neatly with a fixed expectation. I would avoid submitting a request until the displayed availability makes sense to me.
A realistic example: suppose a car needs an unexpected repair a few days before payday, and the mechanic needs payment before the next shift. I’d compare the repair amount with the cash available through the app, take only what is needed for that bill, and leave room for food, transport, and other essentials until payday. If the amount available does not cover the repair, I would not assume that repeated requests can fill the difference; I’d ask the mechanic about timing or payment arrangements and consider other options.
Features That Stand Out
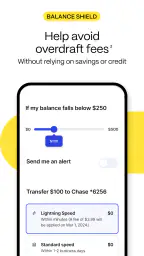
One of the standout features of EarnIn is the "Balance Shield" alert. Imagine getting a heads-up when your account balance is running low. This nifty feature sends you a notification, so you’re never caught off guard. There’s also the "Cash Out" feature, which is, of course, the heart of the app. And did I mention the "Health Aid" feature? It’s an optional service that helps you negotiate medical bills. Honestly, it’s like having a financial buddy in your pocket.
For me, the useful way to think about an alert is as a prompt to check the account, not as a substitute for checking it. A notification can arrive when a balance is low, but the user still needs to decide what to do: pause discretionary spending, move a bill date if possible, or use earned-pay access only when it solves a specific shortfall. That distinction keeps an alert from creating a false sense that the underlying budget is being managed automatically.
The handoff to a bank account is another point to plan around. If the expense has a firm deadline, I would not leave the request until the last moment; I’d check the app’s current process and allow time for the money to become usable. The important question is not simply whether a cash-out can be requested, but whether it will be available before the payment must be made. For a deadline that cannot move, a backup plan matters.
When another option makes more sense
Compared with a credit card, an early-pay app is tied to wages already earned rather than a revolving credit line. That can feel more direct for a one-off timing mismatch, but it does not offer the same kind of ongoing borrowing capacity. A credit card may be more practical for a purchase that needs to be paid at checkout, provided the user can manage the bill and understands its costs. A personal loan is generally a poor fit for a very small, brief gap if it means taking on a longer commitment; conversely, someone facing a larger, persistent shortfall should look beyond repeated early access and address the wider cash-flow problem.
There is also the simple alternative of asking a biller to shift a due date, using savings, or waiting until payday. Those options may take more planning, but they do not bring future wages forward. I’d choose EarnIn when the expense is necessary, the timing is genuinely tight, and I can account for the reduced paycheck afterward. I’d skip it when I need money repeatedly just to cover ordinary costs, when my income is unpredictable, or when a different payment arrangement solves the problem without borrowing against the next pay period.
Costs, limits, and the point where the flow breaks
The app is free to download, but I would still read the cash-out screen carefully before confirming anything and pay attention to any optional contribution or tip presented during the process. A voluntary amount is still money leaving the user’s pocket. If I chose to leave one, I’d include it in the cost of getting the cash early instead of treating it as unrelated to the decision. The practical comparison is the total amount I give up against the value of having the funds sooner.
The workflow can also become frustrating if employment details, work hours, or bank information do not match the app’s expectations. That is especially relevant for people who change shifts often, work multiple jobs, or are paid irregularly. I would not assume that every work arrangement will produce a smooth estimate. If the available amount looks wrong, I’d pause and check the entered details rather than budgeting around money that has not been made available.
There is a broader limitation: an early-pay advance solves timing, not a lack of income. If each cash-out leaves the next payday too tight, the cycle can become self-defeating. I’d use it sparingly and review whether the next check still covers scheduled expenses. For a repeated shortfall, a budget adjustment, savings plan, conversation with a biller, or qualified financial guidance is more useful than treating early access as a permanent part of income.
Who I’d recommend it to
EarnIn is most appealing to someone with earned wages and a short-lived gap between an expense and payday, who can plan around the smaller amount arriving later. The app is free, rated for Everyone, and has a 4.7 average from around 279,000 ratings; its 10 million-plus installs show that many people have tried it, though popularity alone does not tell me whether it fits a particular budget. It runs on Android from version 8.0, and its current version is 16.21.
The audience feedback is substantial, with around 138,000 reviews, but I would still judge the service by my own pay pattern and the terms shown in the app. Someone who wants a long-term credit product, needs a guaranteed amount on a precise schedule, or has no reliable paycheck to plan against should look elsewhere. I’d also avoid using it to fund nonessential spending simply because the option is available.
Why It’s a Game Changer
In a world where financial stress is all too common, EarnIn offers a breath of fresh air. It’s not just an app; it’s a lifeline for those unexpected moments when you need cash pronto. Whether it’s a surprise bill or just making ends meet, having access to your paycheck when you need it is a huge relief. It’s like payday every day, and who doesn’t want that?
Wrapping up, I’d say EarnIn is a must-try for anyone looking to gain a bit more control over their finances. It’s straightforward, it’s fair, and most importantly, it gives you access to your money when you need it most. So, if you’re tired of waiting for payday, give EarnIn a whirl. It might just be the app you didn’t know you needed.
Frequently Asked Questions
What is EarnIn and how does it work?
EarnIn is a financial app that allows users to access part of their paycheck before the actual payday. By connecting your bank account and employer information to the app, EarnIn tracks your work hours and lets you cash out a portion of your earnings whenever needed. This helps in avoiding payday loans and high-interest borrowing by giving you access to your earned money in real-time.
Is EarnIn safe to use with my bank account information?
Yes, EarnIn is designed with security in mind. It uses bank-level encryption to protect your data, ensuring that your sensitive information, such as bank account details, is kept secure. The app only accesses the necessary information to verify your pay and work hours, and it does not store your bank login credentials.
Are there any fees associated with using EarnIn?
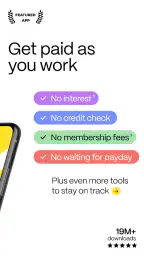
EarnIn does not charge mandatory fees or interest. Instead, it operates on a tip-based model where users can choose to tip an amount they feel is fair for the service. This means you can access your earnings without incurring traditional loan costs or high-interest fees, making it a more affordable option for short-term cash needs.
How much money can I cash out with EarnIn?
The amount you can cash out with EarnIn depends on your earnings and usage of the app. Initially, users can access up to $100 per day, with a maximum of $500 per pay period. These limits can increase over time as you continue to use the app and demonstrate responsible financial behavior.
Does using EarnIn affect my credit score?
No, using EarnIn does not affect your credit score. The app does not perform credit checks when you sign up or use their services. Since EarnIn is not a loan provider but a service facilitating early access to your earned wages, it won't impact your credit history or score in any way.


